Explain the inventory a buyer would inherit
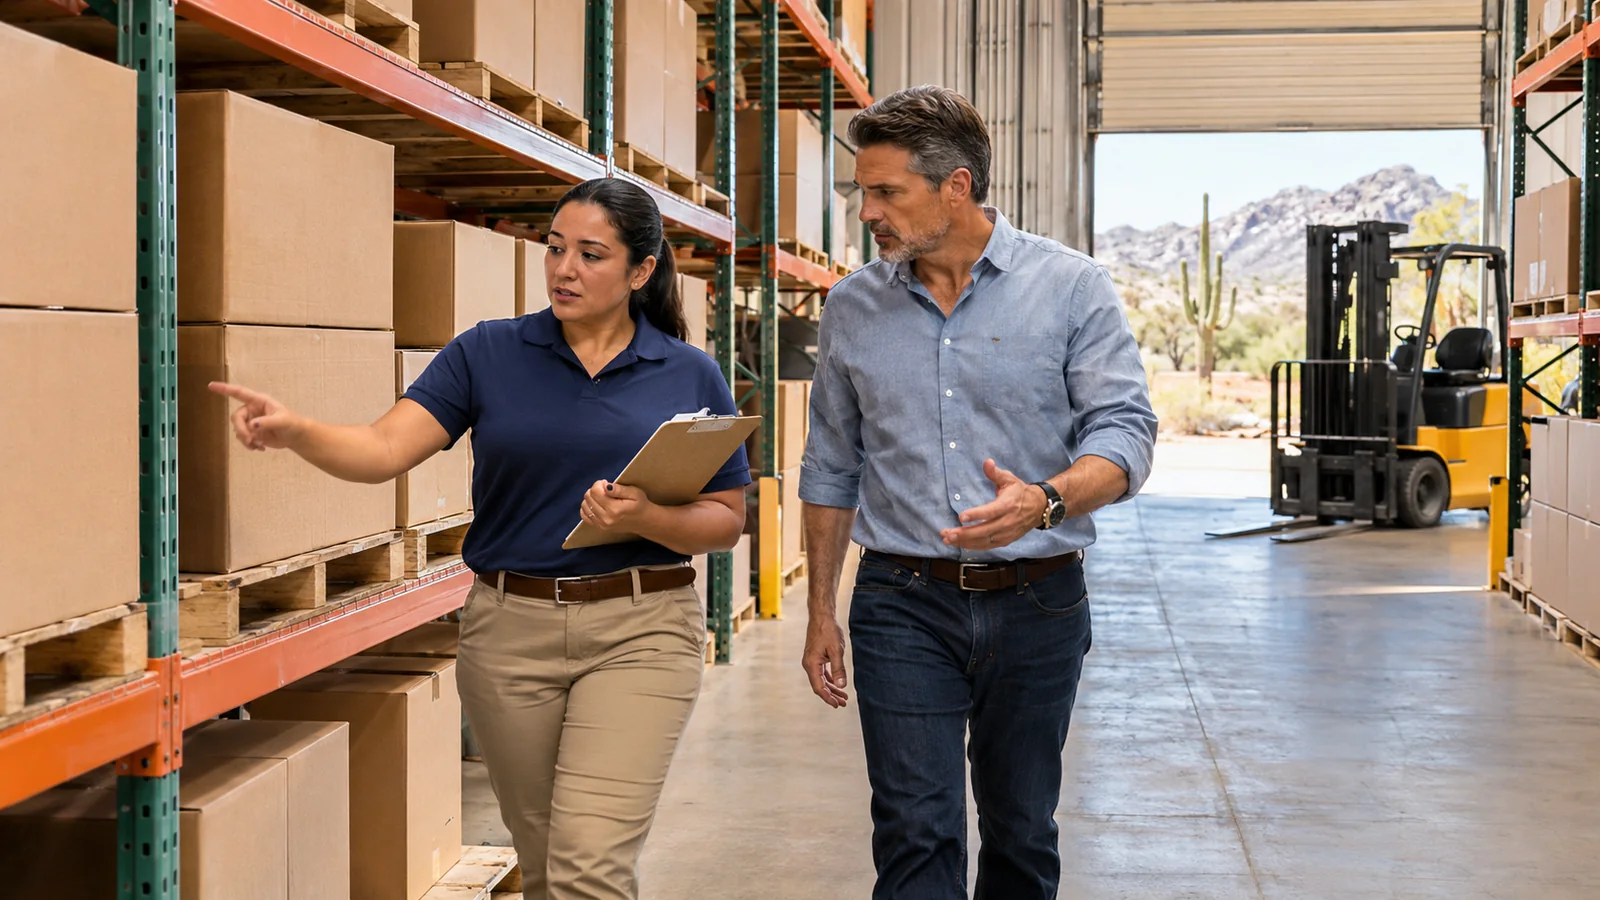
Prepare an inventory aging report and identify damaged, slow moving or obsolete stock. Agree whether inventory is included in the price and how the closing count will be handled.
Do not assume the cost on the books equals what every item is worth. A large inventory balance can increase the buyer’s funding needs without producing a matching increase in earnings.
Make concentration risk visible
Show revenue and gross margin by major customer and product group. A buyer needs to know how much the business depends on a small number of accounts.
Review supplier agreements, credit terms and any exclusive arrangements. Identify permissions or ownership changes that could affect continued supply.
Define normal working capital
Map the time between paying suppliers and collecting from customers. Seasonality, freight costs and stocking needs can change the cash required to keep orders moving.
Address receivables, payables and the inventory target in the offer. Leaving those terms vague can turn the final price discussion into a disagreement at closing.
Review the warehouse obligations
Document storage capacity, equipment leases and the remaining property term. A buyer may need landlord approval or financing for changes before taking over.
If you own the building, model the operating business with a realistic rent expense. Consider the property strategy separately from the sale of the company.
Continue your preparation
Consider inventory, working capital and earnings together before setting a sale price.
Request a private price discussion ↑ or call (602) 555-0181